Opportunity Zones: 2026 Changes and Planning Opportunities for Investors
AI-generated Image
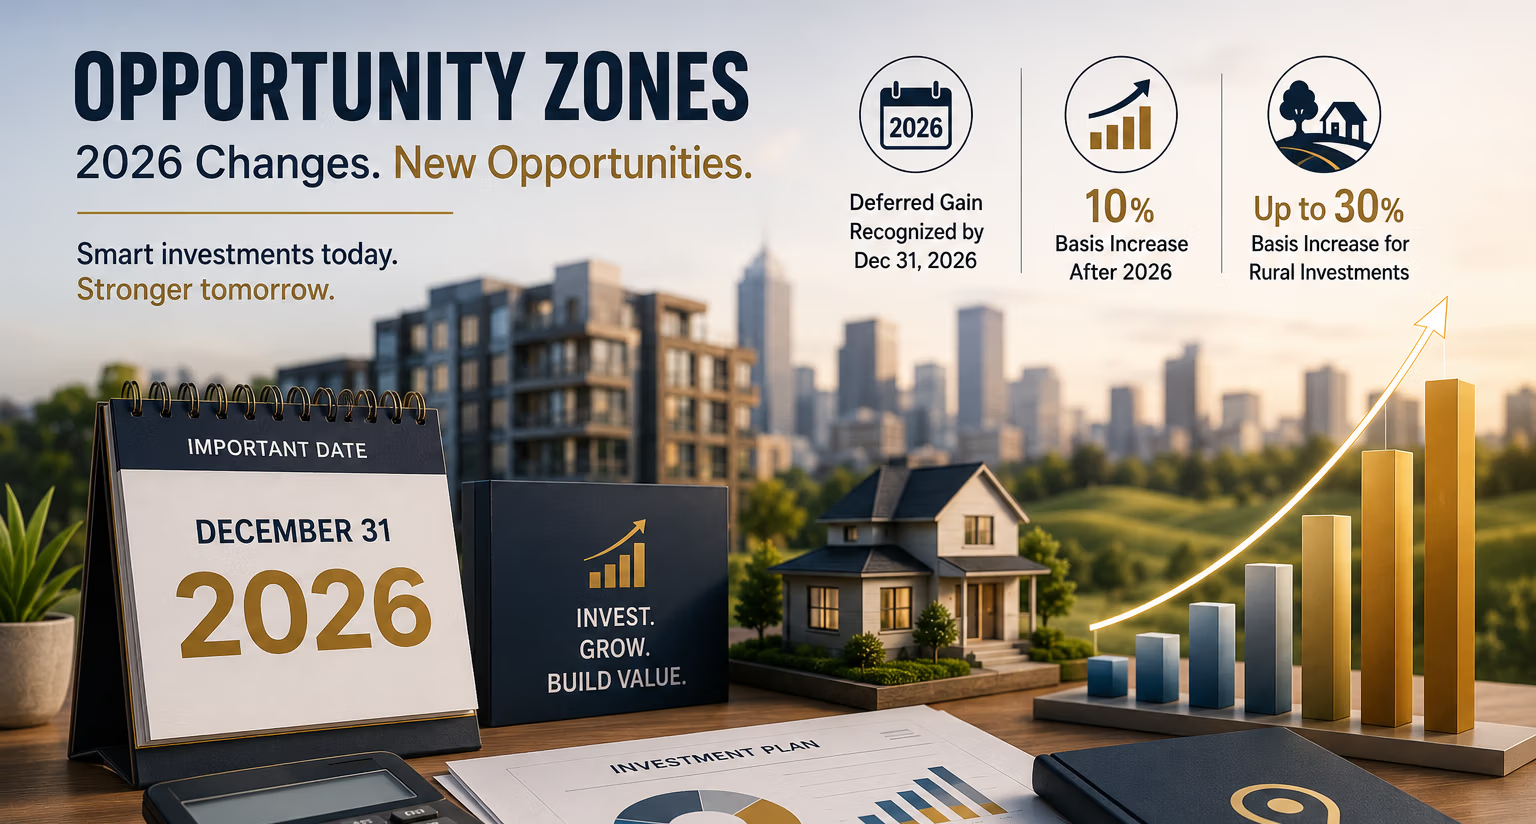
December 31, 2026, is more than just another date on the calendar for Opportunity Zone investors. It could be a major tax-planning milestone.
Investors with existing Qualified Opportunity Fund (QOF) investments may face recognition of previously deferred gains, while investors considering new Opportunity Zone investments will encounter a significantly different set of rules beginning in 2027.
The changes also introduce new incentives for qualifying rural investments, making this an important time to review both existing QOF investments and potential future opportunities.
Important: Opportunity Zone rules are complex. Your tax treatment can depend on when the gain was realized, when you invested in the QOF, the type of investment, holding period, and other requirements. Always consult a qualified tax professional before making investment or tax-planning decisions.
What Is an Opportunity Zone?
An Opportunity Zone (QOZ) is a designated economically distressed community where eligible investors can receive certain federal tax benefits for investing through a Qualified Opportunity Fund (QOF).
A QOF is an investment vehicle that invests in qualifying Opportunity Zone property and generally must meet a 90% investment standard to maintain its qualified status.
The program was designed to encourage private investment in communities that could benefit from new capital, businesses, jobs, and economic development.
How Did the Original Opportunity Zone Tax Benefit Work?
Under the original Opportunity Zone rules, an investor with eligible gain could generally defer federal tax on that gain by investing the appropriate amount in a QOF within the applicable 180-day period.
For existing investments under the original rules, deferred gain is generally recognized in the taxable year that includes December 31, 2026, unless an earlier inclusion event occurs.
That does not necessarily mean the investor must sell the QOF investment in 2026. An investor may continue holding the investment and, if the requirements are satisfied, may still be eligible for the separate 10-year appreciation benefit.
Why December 31, 2026 Matters
If you already own a QOF investment, 2026 deserves a closer look now—not after year-end.
The recognition of previously deferred gain could create a significant tax liability even if you continue holding the QOF investment.
Before the end of 2026, consider reviewing:
- The amount of gain originally deferred
- The date your QOF investment was made
- The structure of the QOF investment
- Whether an inclusion event has already occurred
- Your expected 2026 tax liability
- Your available cash to fund the tax liability
- Your expected QOF holding period
- Whether you plan to retain the investment beyond 2026
- How the investment fits into your estate and overall tax strategy
A proactive review can give you more time to prepare for the tax bill and evaluate your options.
What Changes for Opportunity Zones After 2026?
The One, Big, Beautiful Bill Act (OBBBA) made significant changes to the Opportunity Zone program.
The program was made permanent, and a new round of Opportunity Zone designations begins January 1, 2027, with additional designation rounds generally occurring every 10 years.
For investors considering new QOF investments, the rules after 2026 are therefore different from the rules that applied to the original Opportunity Zone program.
Here are the major changes to understand.
1. A New Round of Opportunity Zones Begins in 2027
The next round of QOZ designations takes effect January 1, 2027.
That means investors considering a new QOF investment should not automatically assume that today’s Opportunity Zone map will remain the same.
States are going through the nomination process for the new designations, and Treasury and the IRS expect to identify the designated tracts before January 1, 2027.
Planning point: If you’re considering a 2027 investment, verify that the specific property or business is located in a qualifying tract under the new rules.
2. New Five-Year Basis Benefit for Investments After 2026
One of the major changes applies to amounts invested in QOFs after December 31, 2026.
Under the new rules, if the qualifying investment is held for at least five years, the investor generally receives a 10% increase in basis attributable to the deferred gain.
In simple terms, the new rules provide a fresh five-year timeline for the basis benefit rather than tying the benefit to the original 2026 deadline.
This creates a new planning consideration for investors making QOF investments beginning in 2027.
3. A Potential 30% Benefit for Qualifying Rural Investments
The new rules provide an enhanced basis benefit for certain investments in qualified rural opportunity funds.
For qualifying rural investments held for at least five years, the basis increase can generally be 30% instead of 10%.
This can make qualifying rural projects particularly interesting for investors evaluating long-term Opportunity Zone strategies.
However, not every property outside a major city automatically qualifies. Specific statutory requirements apply to the definition of a rural area and to qualified rural opportunity funds.
4. The 10-Year Appreciation Benefit Remains Important
The long-term Opportunity Zone strategy does not end with the 2026 transition.
If an investor holds a qualifying QOF investment for at least 10 years and meets the applicable requirements, the investor may generally elect to adjust the basis of the QOF investment to its fair market value when the investment is sold or exchanged.
This can potentially exclude federal income tax on qualifying appreciation generated after the QOF investment.
Important: This benefit is separate from the tax treatment of the originally deferred gain. Investors should evaluate both pieces independently.
5. Rural Property Gets a More Favorable Improvement Rule
The Opportunity Zone changes also provide a significant benefit for certain rural real estate projects.
For qualifying tangible property located in a QOZ that is entirely within a rural area, the required substantial-improvement threshold was reduced from 100% to 50%, effective July 4, 2025.
That means qualifying rural property may require a substantially smaller investment in improvements to satisfy the applicable substantial-improvement test.
This can be particularly relevant to real estate investors, developers, and businesses evaluating renovation or redevelopment projects.
The rural definition is specific. Generally, it excludes cities or towns with populations greater than 50,000 and urbanized areas contiguous and adjacent to such cities or towns.
Existing QOF Investments vs. New Investments After 2026
The most important distinction for investors is when the QOF investment is made.
The exact tax consequences depend on the gain date, investment date, QOF structure, type of property, holding period, and other requirements.
Opportunity Zone Planning Strategies for 2026 and 2027
The changes create several planning opportunities—but they also make timing more important.
1. Review Existing QOF Investments
If you already have a QOF investment, determine how much deferred gain you may need to recognize for 2026.
Also consider whether you intend to continue holding the investment after the recognition date.
2. Estimate Your 2026 Tax Liability Early
Don’t wait until you file your 2026 return to discover that a significant deferred gain has become taxable.
Work with your tax advisor to estimate the potential liability and consider how you will fund it.
3. Evaluate 2027 Investments Before Investing
If you’re considering a new QOF investment, understand the post-2026 rules before committing capital.
Compare the potential tax benefits with the investment’s expected return, risk, liquidity, and required holding period.
4. Explore Qualifying Rural Opportunities
The potential 30% basis increase and the favorable 50% substantial-improvement threshold may make certain rural Opportunity Zone projects worth evaluating.
Real estate investors and developers should determine whether the specific property and investment structure satisfy the applicable rural requirements.
5. Model the Tax and Investment Outcomes
ax benefits should never be the only reason to make an investment.
Before investing, consider:
- Expected investment return
- Tax benefits
- Investment risk
- Liquidity
- Holding period
- Cash-flow requirements
- Estate-planning considerations
- Potential federal and state tax consequences
A tax-efficient investment is not necessarily a good investment if the underlying economics do not make sense.
Why Investors Should Review Their OZ Strategy Now
Opportunity Zones are entering an important transition period.
For existing investors, December 31, 2026, is a major tax-recognition milestone. For investors considering new QOF investments, January 1, 2027, begins a new Opportunity Zone framework with new designation rules and additional incentives, particularly for qualifying rural investments.
That makes 2026 an ideal time to review your strategy—not simply react to the changes after they take effect.
Key Takeaway
Opportunity Zones are changing, but the planning opportunities are evolving rather than disappearing.
If you already have a QOF investment, start preparing for the potential 2026 deferred-gain recognition now.
If you’re considering a new investment, understand the 2027 rules, new five-year basis benefit, potential 30% rural benefit, and 10-year appreciation strategy before committing capital.
Most importantly, evaluate the tax benefits alongside the investment’s risk, return, liquidity, and long-term objectives.
Ready to Review Your Opportunity Zone Strategy?
At SAI CPA Services, we help investors, business owners, and real estate professionals evaluate tax-planning opportunities and understand how major tax-law changes may affect their financial decisions.
Whether you already own a QOF investment or are considering an Opportunity Zone investment for 2027, now is the time to review your options.
Contact SAI CPA Services to schedule a tax-planning consultation and develop an Opportunity Zone strategy aligned with your investment and financial goals.
This article is provided for general informational purposes only and does not constitute tax, legal, or investment advice. Opportunity Zone rules are complex and subject to IRS guidance and individual circumstances. Consult a qualified tax, legal, or investment professional before making investment or tax-planning decisions.